Estate & Probate Appraisals · Date of Death · USPAP Compliant
For estate attorneys, executors, and trustees

Estate appraisals, from one car or a coin collection to a whole house or a family business

We appraise everything in an estate except the real estate: the contents of the house, firearms, cars and boats, coins, jewelry, art, collections, and interests in a business. Each gets a fair market value as of the date of death, in a written USPAP report.

Probate inventoriesForm 706 estate taxDividing among heirsBusiness interestsPast dates of death
5.0 ★ Google rating from 89 reviewsRead client reviews
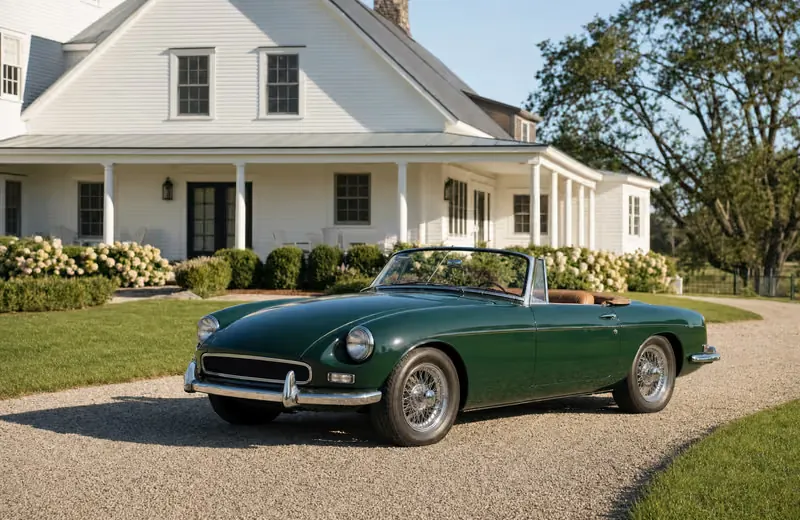
A dining room with a set table, a china cabinet, rugs, and paintingsClassic hunting rifles and a shotgun in a walnut gun cabinet in a family studyA vintage green roadster parked in front of a white farmhouse

Most estates are appraised from the family's photos and lists, with an in-person inspection where the property calls for one, and larger estates are split between specialists. Estate attorneys, personal representatives, and trustees can send clients straight to us. We quote a fixed fee in an engagement letter before any work starts.

◆  Client names, amounts, and identifying details have been withheld to protect confidentiality.
◆  For illustrative purposes only. Photos show the kinds of property we appraise, not client property. The case studies describe the kinds of estates we appraise and the rules that applied. They are not tax or legal advice; the estate's filings are for its personal representative and advisers to decide.
What We Appraise

Everything in the estate but the house itself

One estate often holds several kinds of property. We value each with an appraiser who knows it, and bring them together for the inventory, the return, or the heirs.

A desk with a financial model on the monitor in a bright office
Business Valuation

Business interests in the estate

When the estate owns part of a company, our business valuation team values the interest as of the date of death, for Form 706, the probate inventory, or a buyout among heirs.

  • Closely held companies and family businesses
  • LLC and partnership interests, including family limited partnerships
  • Holding companies that own real estate or investments
  • Promissory notes, restricted shares, and private fund interests
How It Works

Four steps, mostly from the family's photos

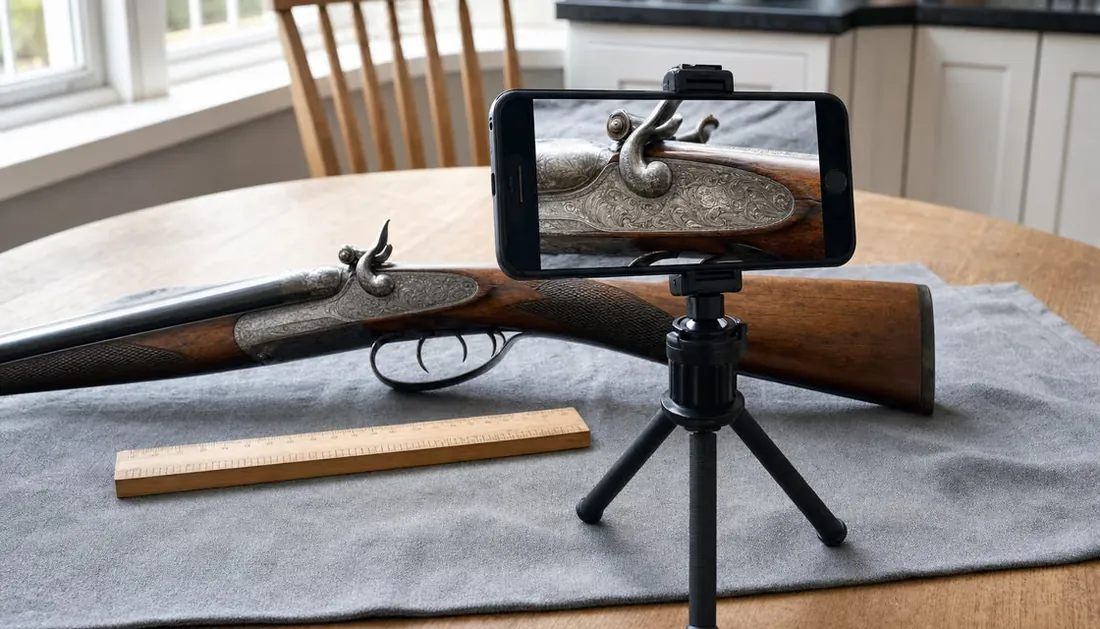
A phone on a small tripod photographing the engraved side plate of a vintage shotgun
1

Send photos and a list

Photos of each item or room, and whatever paperwork the family has: an inventory, receipts, VINs, or serial numbers.

A clipboard and pen on a desk beside a set of car keys
2

Get a fixed fee

We scope the estate and quote a fixed fee in an engagement letter before any work starts.

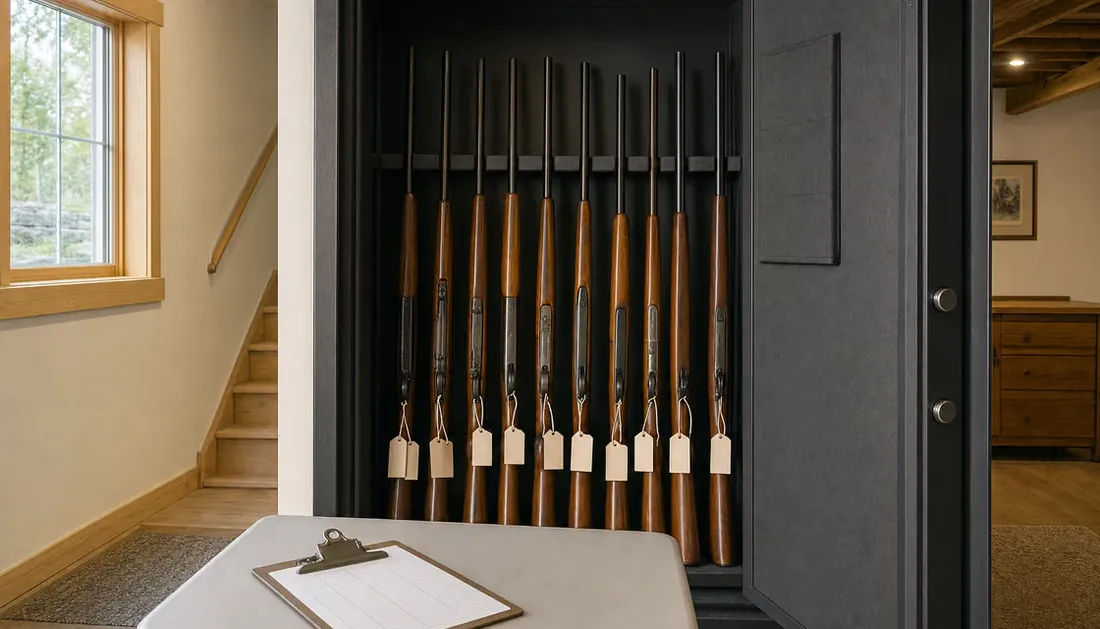
An open gun safe holding tagged rifles and shotguns, a clipboard in front
3

Matched to a specialist

A credentialed appraiser for each kind of property, with an in-person inspection where the property calls for one.

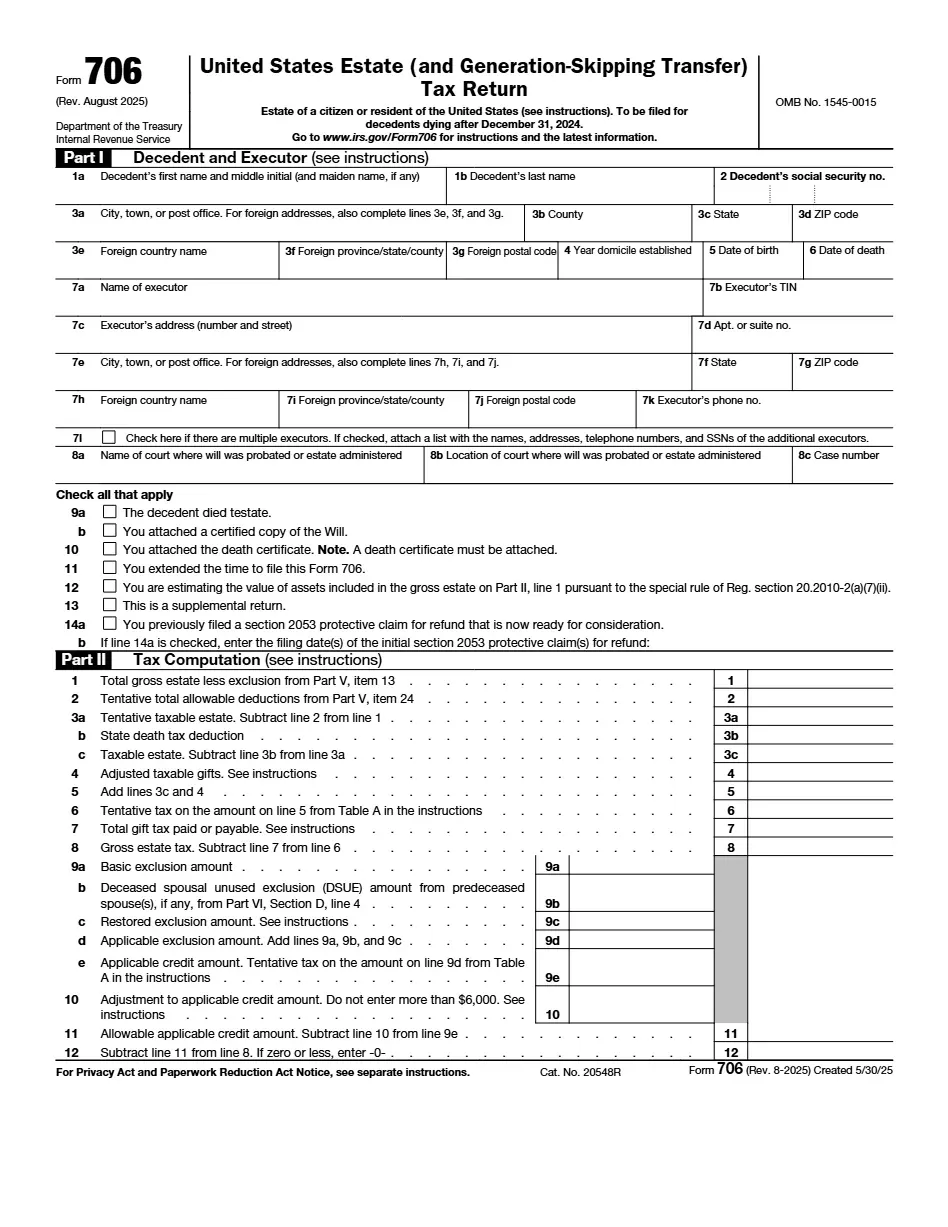
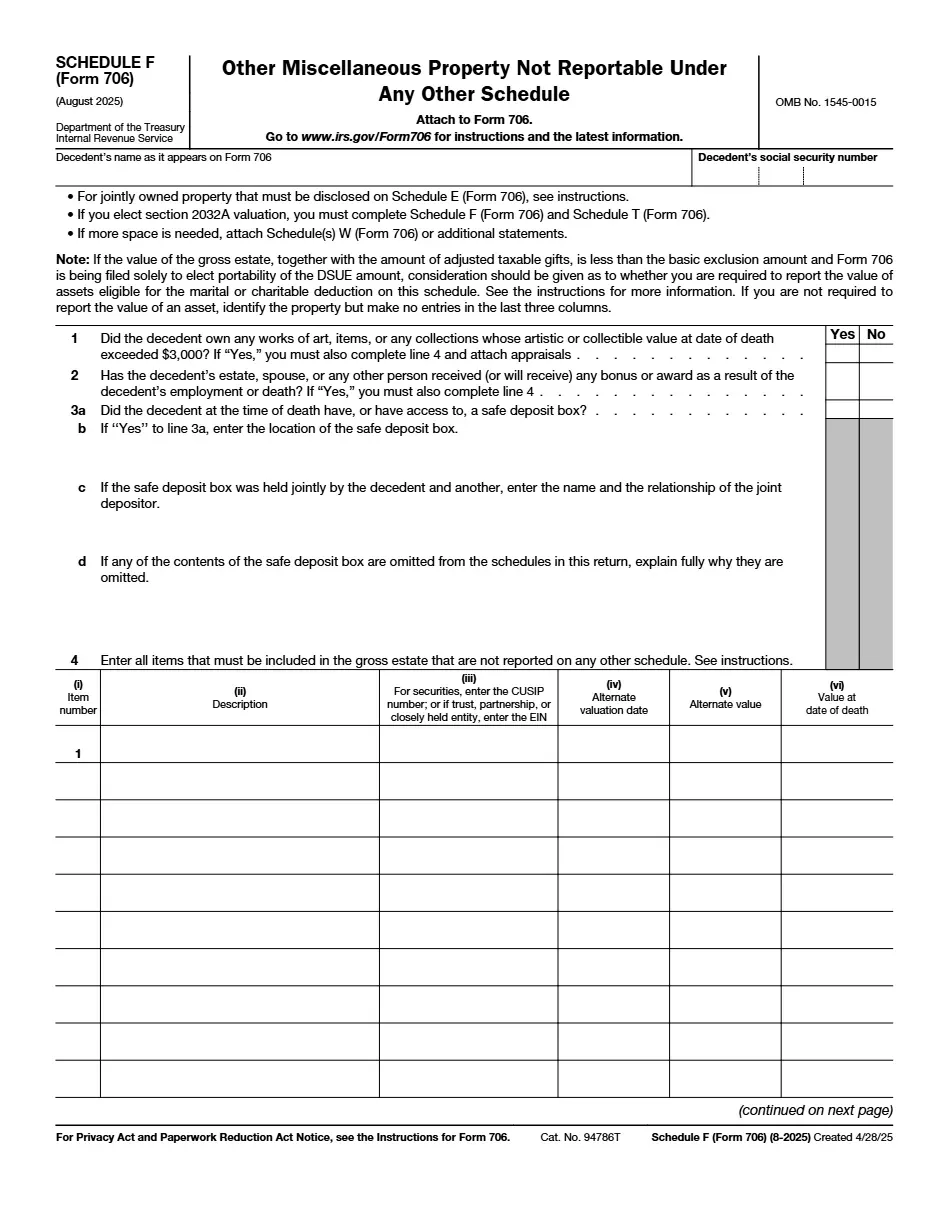
The first page of IRS Form 706
4

Receive the report

A written USPAP report with fair market value as of the date of death, for the probate court, Form 706, or the heirs.

Summary

Engagements at a glance

EngagementPurposePropertyState
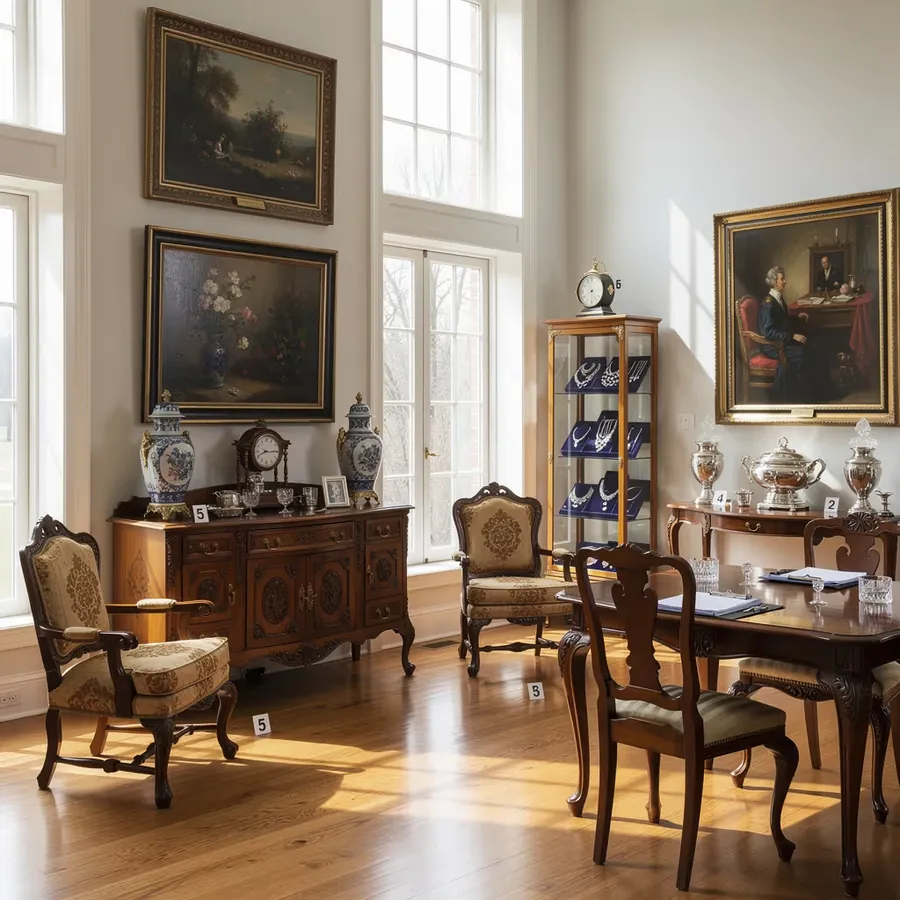
A dining room with a set table, a china cabinet, rugs, and paintingsContents of a family home, room by room Estate tax (Form 706) Household contents Delaware
A pearl necklace, a sapphire bracelet, emerald earrings, and a diamond ringFurniture and jewelry for a probate inventory Probate inventory Furniture, jewelry Maryland
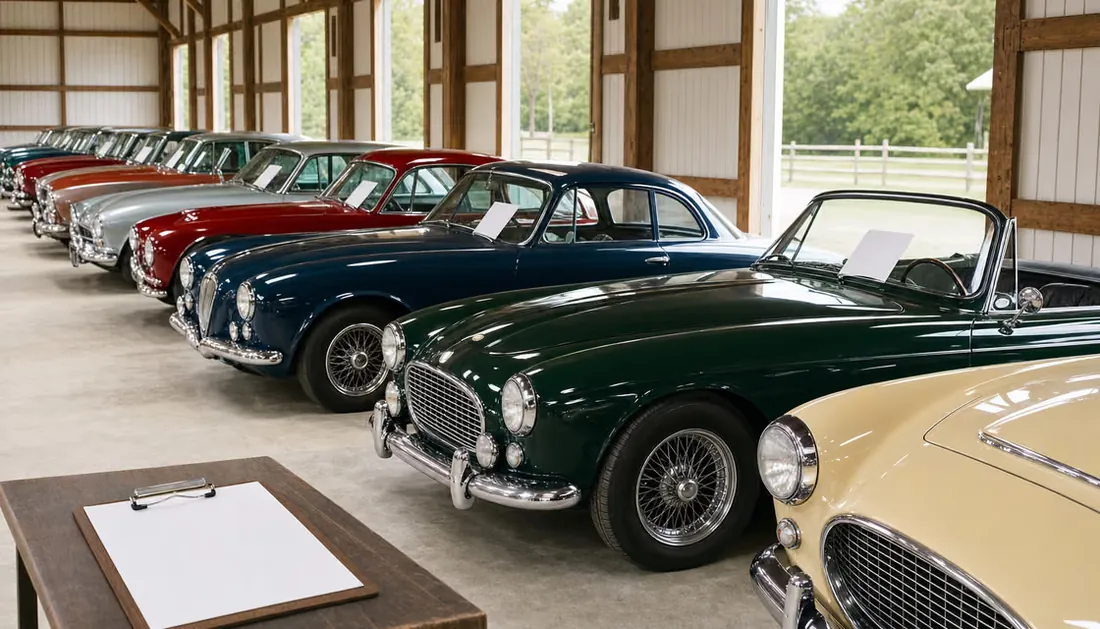
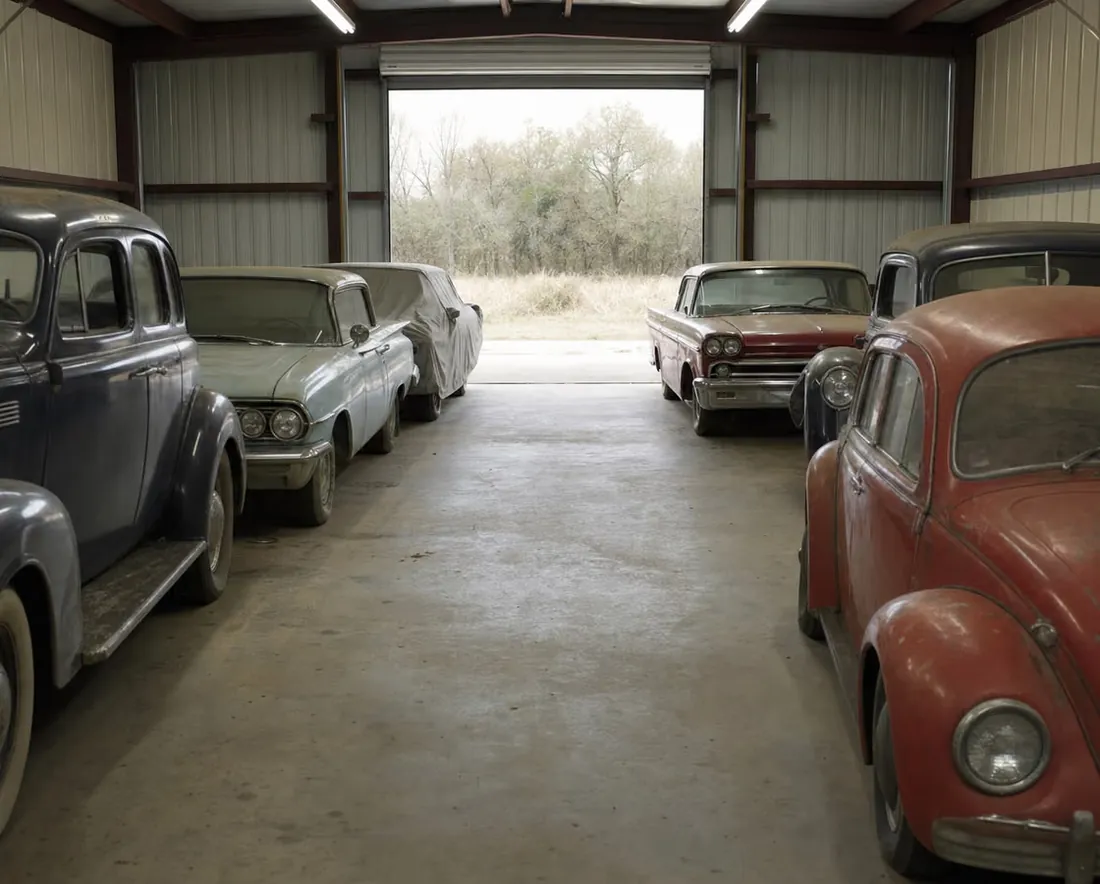
Older cars stored in a garageCars, boats, and motorhomes for probate courts Probate court Vehicles, boats, trailers Ohio
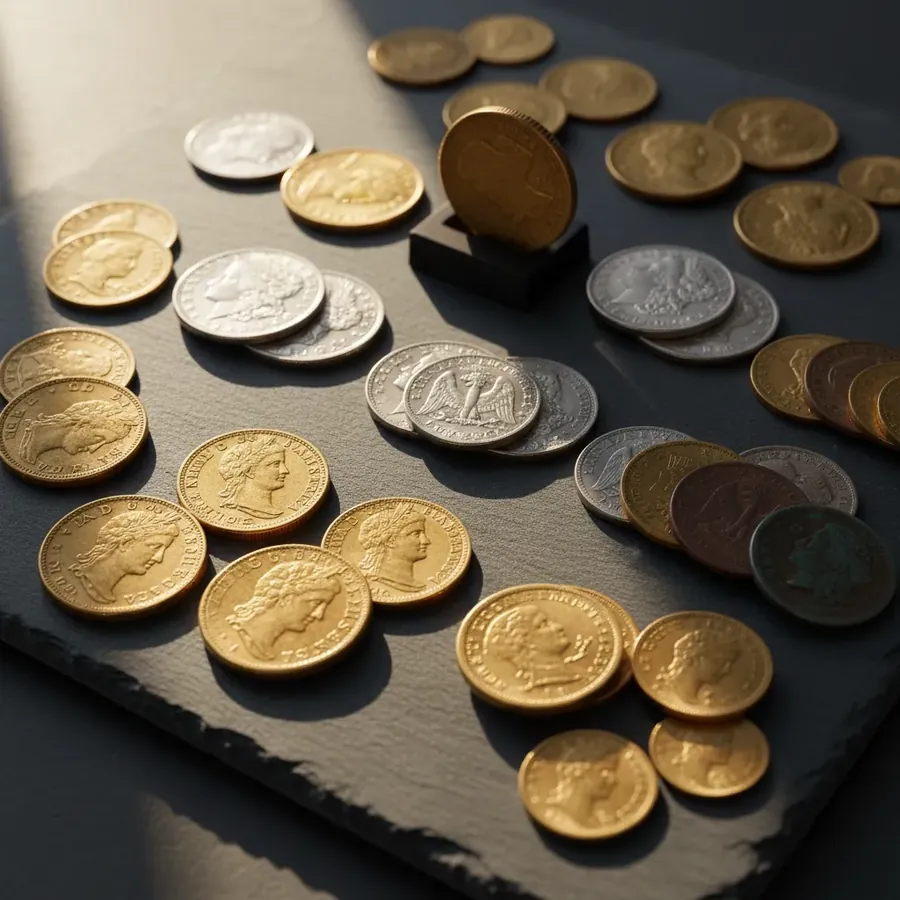
Gold and silver coins laid out on a slate trayA late father's coin collection, for three heirs Estate distribution Coins Florida
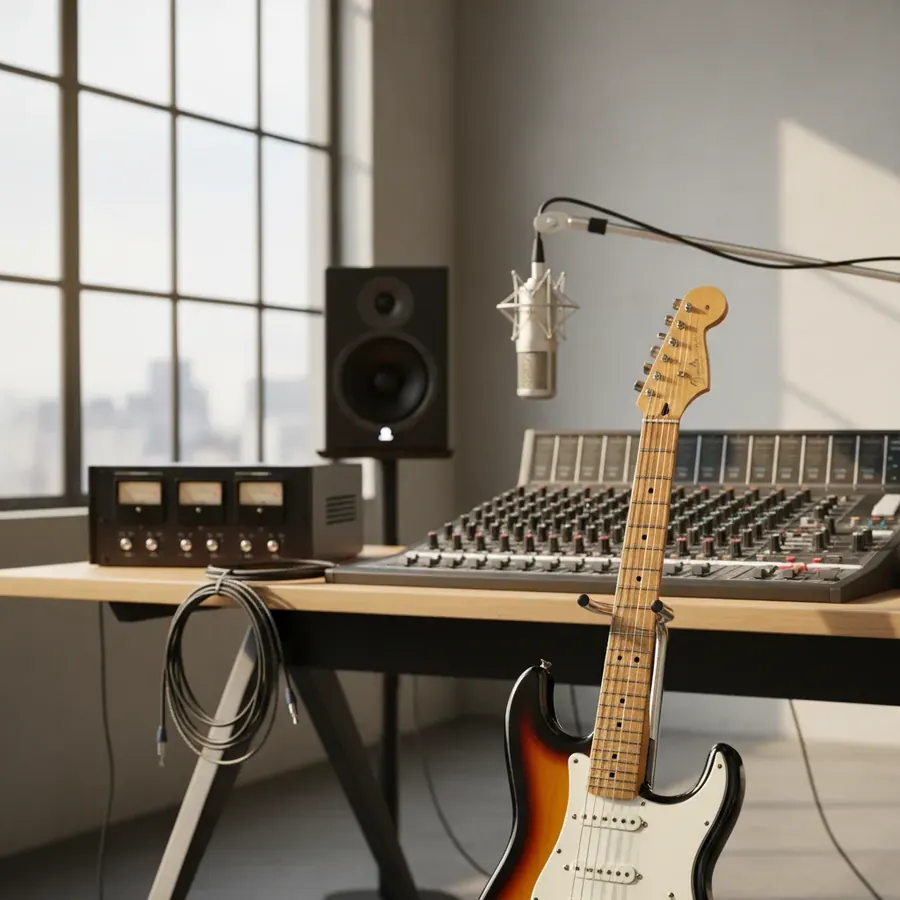
An electric guitar beside a mixing desk in a studioSix guitars and a painting, two specialists Estate tax Musical instruments, fine art New Jersey
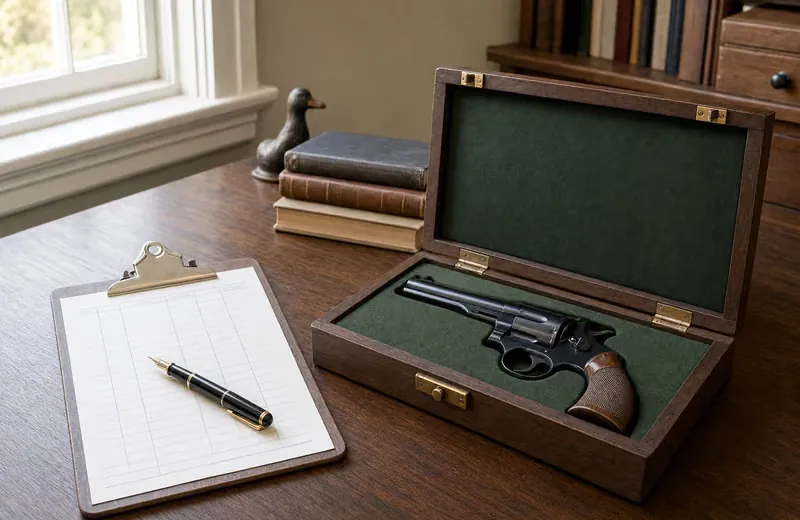
A vintage revolver in an open, felt-lined wooden case beside a clipboardAn antique firearms collection Estate settlement Firearms Florida
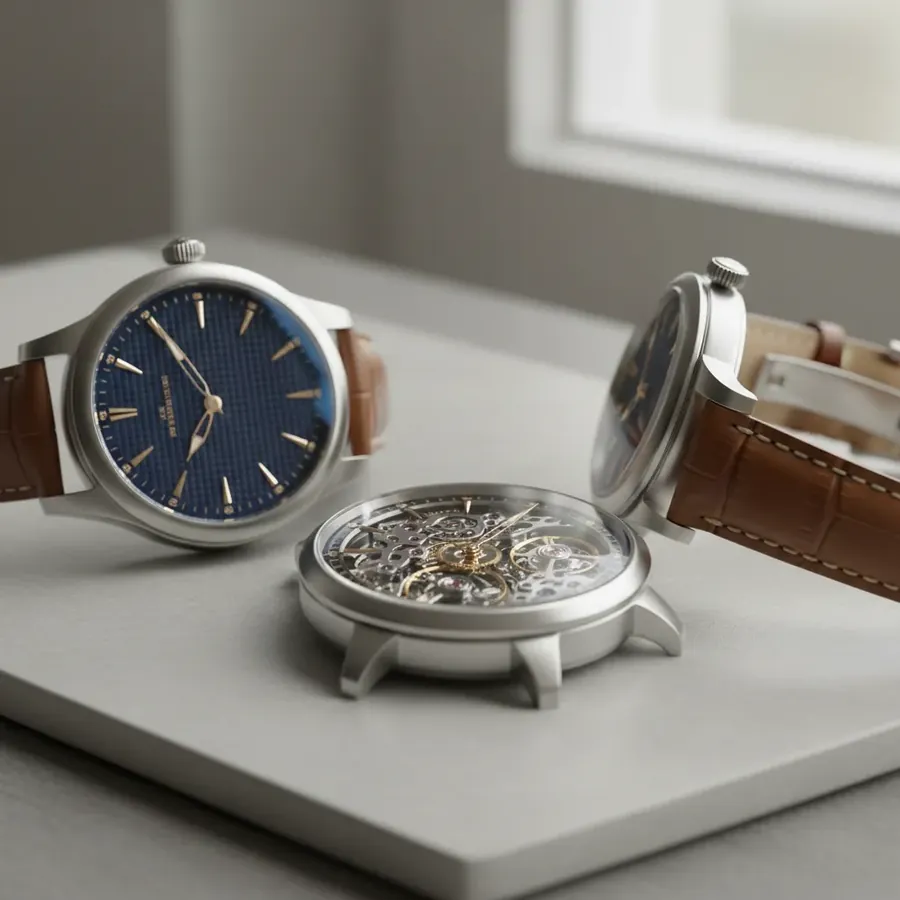
Two wristwatches on a display standWatches and a collector car, four years on Estate tax Watches, collector car Pennsylvania
A corporate seal embosser beside operating documents on a deskInterests in three small LLCs Estate tax (Form 706) LLC interests New York
An open-plan company office with desks and a glass meeting roomTwo family-held operating companies Estate planning Operating companies California
Probate · Form 706 · Heirs

When an estate needs an appraisal, and what it does

The rules that most often call for an appraisal of an estate's personal property or business interests, and what our report provides. Personal representatives should confirm their own filings with the estate's attorney or accountant.

Probate inventory
Date-of-death values

Estates file an inventory of the decedent's property with date-of-death values. An appraisal supports the values of household contents, collections, jewelry, and vehicles on it.

Valuation date
Date of death

Or the alternate valuation date six months later, if the executor elects it; it applies to the whole estate and only where it lowers both the gross estate and the tax (IRC §2032). We also value as of past dates, for estates settled years later.

Standard of value
Fair market value

The price between a willing buyer and a willing seller, neither under any compulsion and both knowing the relevant facts. Not a forced-sale price, and measured where such items are most commonly sold to the public (Treas. Reg. §20.2031-1(b)).

Household and personal effects
$3,000

Where articles of marked artistic or intrinsic value, such as jewelry, silverware, paintings, antiques, rugs, or coin and stamp collections, pass $3,000 in total, an expert appraisal is filed with Form 706 under oath. Effects are itemized room by room; same-room articles worth $100 or less each may be grouped (Treas. Reg. §20.2031-6).

Form 706
Nine months

Due nine months after the date of death, with a six-month extension of time to file available on Form 4768.

Heirs' basis
IRC §1014

The value reported generally becomes the beneficiary's income tax basis, so it follows the property into any later sale. An appraisal documents that basis even when no estate tax is due.

Business interests
Treas. Reg. §20.2031-3

An interest in a closely held company, LLC, or partnership is valued on all relevant factors, including a fair appraisal of its assets and its demonstrated earning capacity, with closely held stock valued on the factors in Rev. Rul. 59-60.

Dividing among heirs
Item by item

A value for each item or lot gives the heirs a common basis for dividing property, or for buying out one another's share.

What we deliver
USPAP report

Identifies each item or lot, describes its condition, explains how the value was reached, and concludes fair market value as of the date of death, with the appraiser's signed certification and qualifications.

IRS Form 706, Schedule F, Other Miscellaneous Property
Household goods, art, and collections are reported on Form 706, Schedule F. Our report supports the values listed there.
Credentials

The appraisers behind your estate's appraisal

Every estate goes to a credentialed appraiser matched to the property, whether household contents, art and antiques, coins, jewelry, firearms, vehicles, or a business interest, and larger estates are split between specialists. Our appraisers include a former IRS art appraiser, a GIA Graduate Gemologist, an Antiques Roadshow appraiser, and business appraisers who have prepared hundreds of gift and estate tax valuations. Every report is prepared in accordance with USPAP. Click a profile for full credentials.

Memberships and credentials across the teamInternational Society of AppraisersAmerican Society of AppraisersAppraisers Association of AmericaCertified Appraisers Guild of AmericaNational Association of Certified Valuators and AnalystsThe Appraisal Foundation

Personal property

Joe Kattan

Joe Kattan

Owner & CEO
Bain & Company
Engagement oversightAppraiser matching

Owner and CEO of AppraiseItNow. A former Bain & Company consultant, Joe acquired the firm in 2024 and has led its growth since, bringing Bain's standard of analytical rigor to how every valuation engagement is scoped, staffed, and reviewed.

Full credentials ↓Collapse ↑

Joe is the owner and CEO of AppraiseItNow. Before acquiring the firm, he was a consultant at Bain & Company, where he advised executive teams on strategy, growth, and investment decisions. The work demanded rigor under deadline: framing the question that actually matters, building the analysis that answers it, and defending every number in the room. He holds AppraiseItNow's valuation work to that same standard, where a conclusion is only as strong as the evidence and reasoning behind it.

Joe acquired full ownership of AppraiseItNow in 2024 and has led its growth since, expanding the practice across business valuation, fine art, and complex machinery and equipment. He has also invested heavily in the firm's technology, so clients get faster answers and every report benefits from a consistent, well-supported process. He oversees engagement quality across the practice and matches each estate to the right credentialed appraiser on the team, splitting larger estates between specialists.

Steve Roach

Steve Roach

ISA Certified Member · AQB Certified USPAP Instructor
Fine artRare coinsDecorative artsCollectibles

An art appraiser at the Internal Revenue Service from 2016 to 2025, where he made fair market value determinations for more than 3,000 objects in federal income, estate, and gift tax cases. Steve appraises fine art, decorative arts, rare coins, and high-value collectibles.

Full credentials ↓Collapse ↑

Steve has appraised personal property since 2007. From 2016 to 2025 he was an art appraiser with the IRS's Art Appraisal Services in Washington, DC, where he conducted fair market value determinations for more than 3,000 objects collectively valued at more than $1.2 billion, in support of federal income, estate, and gift tax cases. He also assessed charitable contributions and appraised donated property for tax reporting, served as a Treasury-wide authority on USPAP, and developed expertise in artists' estates, fractional gifts, and other challenging situations.

His work spans fine art from Old Masters to contemporary works, with a particular focus on Impressionist and Modern art, as well as decorative arts and high-value collectibles. Earlier in his career he directed an auction house's trusts and estates department, held a fixed appointment as an associate specialist in 19th century European art, and graded rare coins professionally. He was Editor-in-Chief of Coin World from 2012 to 2015 and then its Editor-at-Large.

Steve is a Certified Member of the International Society of Appraisers, where he has served on the board of directors and as treasurer, teaches the 7-hour and 15-hour USPAP courses, and co-teaches the Appraisal of Fine Art course. He is an Appraisal Qualifications Board Certified USPAP Instructor with The Appraisal Foundation. He holds a JD from The Ohio State University Moritz College of Law and a BA in History of Art and Organizational Studies from the University of Michigan.

Anne Hay

Anne Hay

ISA AM
Household contentsFurnitureAntiquesApparel & textiles

An Accredited Member of the International Society of Appraisers who appraises furniture, artwork, antiques, luxury apparel, and household contents, primarily for IRS tax filings. For a decade Anne owned an estate sale company that bought entire estates and ran sales from setup through cleanout.

Full credentials ↓Collapse ↑

Anne appraises many kinds of personal property, including luxury apparel, furniture, artwork, antiques, and business assets, primarily for IRS tax filings, and researches and writes appraisals for estates, probate, insurance, divorce, and charitable donations.

From 2000 to 2010 she owned an estate sale company, buying entire estates, consigning items to auction, and running complete estate sales from setup and research through the sale and cleanout. She later managed item intake and auction estimates at an auction gallery and researched, photographed, and priced jewelry and vintage goods for online sale.

Anne is an Accredited Member of the International Society of Appraisers and has completed the ISA Core Course in Appraisal Studies and USPAP, with further coursework in appraising silver, Oriental rugs, antiques, furnishings and decorative arts, and ivory regulation and valuation. She holds a BA from Brandeis University.

Ashley Innes

Ashley Innes

MA · ISA AM
Asian artMusical instrumentsAntiques

An Asian art specialist who has provided USPAP-compliant appraisals since 2017, and who chairs the International Society of Appraisers' Antiques, Furnishings, and Decorative Arts committee. Ashley appraises Asian art, musical instruments, and general personal property.

Full credentials ↓Collapse ↑

Ashley has worked as an Asian art specialist since 2017, providing USPAP-compliant appraisals, art advisory, and specialist research. Since 2021 she has appraised personal property as a member of the International Society of Appraisers, for purposes including noncash charitable donations, insurance claims, and equitable distribution.

She chairs the ISA's Antiques, Furnishings, and Decorative Arts committee, where she gives and coordinates presentations on appraisal methodology and edits the committee's education manual, serves on the committee that runs the ISA's annual appraisal conference, and writes about the art market for the ISA.

Ashley holds a Master of Arts in History of Art and Archaeology, with distinction, and a Postgraduate Diploma in Asian Art from SOAS, University of London; a Master of Studies in Musicology from the University of Oxford; and a BA in Music, magna cum laude, from Scripps College. She has studied art law at Sotheby's Institute of Art and works professionally in German.

Henry Platts

ASA Candidate, Personal Property · FFL / SOT
FirearmsCollector cars

A firearms and collector car appraiser who since 2014 has appraised, bought, and sold more than 2,000 firearms, and since 2012 more than 200 collector automobiles. Henry has valued everything from single pieces to estate collections numbering in the hundreds.

Full credentials ↓Collapse ↑

Henry handles firearms year-round as a Federal Firearms Licensee and Special Occupational Taxpayer. His work centers on the American makers collectors prize most, Colt, Winchester, Smith & Wesson, and Browning, along with antique, military, foreign, and NFA-regulated arms, and on what drives their value: factory configuration and finish confirmed by serial number, originality, and condition.

In collector automobiles he is a concours judge for the Jaguar Clubs of North America and the Mercedes-Benz Club of America, and belongs to eleven marque clubs and registries.

Henry has been a Candidate member of the American Society of Appraisers in Personal Property since 2015, has completed the Society's personal property coursework and its automotive specialty course, and prepares his reports in compliance with USPAP, most recently completing the 7-hour National USPAP Update in October 2026. He holds a master's degree in United States History and served as museum manager for Reno County, Kansas, from 2017 to 2019, training he applies to research into provenance, production records, and historical significance.

Shelly Devine

Shelly Devine

GG (GIA) · CMA (NAJA) · RMV
JewelryDiamonds & gemstonesWatches

A GIA Graduate Gemologist and Certified Master Appraiser with more than 20 years in the fine jewelry and gemstone industry, eleven of them specializing in appraisal. Shelly appraises fine jewelry, including antique, estate, and designer pieces, diamonds, colored gemstones, and timepieces.

Full credentials ↓Collapse ↑

Shelly has more than 20 years of consecutive experience in the fine jewelry and gemstone industry, including more than eleven years specializing in jewelry appraisal for insurance, estate, fair market, and hypothetical valuations. She has deep knowledge of diamond grading, colored stone identification, and value analysis based on market data, and prepares USPAP-compliant reports for legal, insurance, and private clients.

She is a Graduate Gemologist of the Gemological Institute of America, with GIA's Graduate Diamonds and Graduate Colored Gemstones diplomas, a Certified Master Appraiser of the National Association of Jewelry Appraisers, a Registered Master Valuer, and a Candidate Member of the American Society of Appraisers.

Marnie Erkelens

Marnie Erkelens

CAGA Certified Appraiser
VehiclesFine artBooks & ephemeraFurnishings

A professional appraiser since 2014, certified by the Certified Appraisers Guild of America. Marnie appraises fine art, collectibles, textiles, books, antiques, furnishings, and vintage and specialty vehicles, drawing on a background in classic car restoration.

Full credentials ↓Collapse ↑

Marnie's practice covers a broad range of personal property: fine art and sculpture from marble to bronze, collectibles from porcelain figurines to firearms, textiles, historic books, pamphlets and religious ephemera, antiques, furnishings, and vintage and specialty vehicles. Her background in classic car restoration, and a network of fabricators, mechanics, and automotive body specialists, inform her vehicle work.

She has worked closely with legal teams and insurers on appraisals for divorce settlements, estate planning, and insurance coverage, including valuations of entire households for the fair division of marital property. She is certified by the Certified Appraisers Guild of America.

Robert Bortner

CAGA
Household contentsAsian antiquesCeramics & silverCollector cars

Has appraised personal property since 2016, with a primary focus on estate liquidations and valuations. Bob's core specialty is residential contents, alongside classic and collectible automobiles, tools, business inventories, and Asian, European, and American antiques.

Full credentials ↓Collapse ↑

Bob has appraised a diverse range of personal property since 2016 for estates, divorce, bankruptcy, insurance, and businesses. His core specialization is residential contents, and he also has extensive experience with classic and collectible automobiles, tools, and business inventories. He helps families value their household possessions and decide whether to sell, donate, or otherwise dispose of them.

He has more than 17 years of experience collecting and trading American, Asian, and European antiques and vintage items, including toys, stamps, coins, and furniture, and co-owns an antiques business specializing in Chinese, Japanese, English, and American ceramics, jewelry, silver and silver plate, and glass. He is a member of the Certified Appraisers Guild of America.

Jasmani Francis

AAA · JD
Sports memorabiliaAmericana

A sports memorabilia and collectibles appraiser on Antiques Roadshow since 2007, and an attorney admitted in Illinois since 2009. Jasmani values high-profile sports and Americana memorabilia and reviews and drafts USPAP-compliant reports.

Full credentials ↓Collapse ↑

Jasmani has appeared as a sports memorabilia and collectibles appraiser on the nationally televised Antiques Roadshow since 2007, examining high volumes of sports memorabilia and Americana. Since 2017 he has also valued high-profile sports and Americana memorabilia as an appraisal consultant, reviewing and drafting USPAP-compliant reports and speaking to investment advisors and asset managers about the collectibles market.

Earlier, he researched provenance and wrote catalog descriptions for sports memorabilia and Americana auctions. He earned his JD from The John Marshall Law School in Chicago and was admitted to the Illinois bar and the U.S. District Court for the Northern District of Illinois in 2009, and holds a BA from Southern Illinois University.

Brandy Marie Selikson

ISA
FurnitureDecorative artsHeirloomsCollectibles

A personal property appraiser and member of the International Society of Appraisers who values antique, vintage, and contemporary furniture, decorative arts, heirlooms, and collectibles. Brandy spent seven years with an online estate sale and auction company.

Full credentials ↓Collapse ↑

Brandy brings a background in photography, cataloging, and managing the sale of valuable items. From 2017 to 2024 she worked for an online estate sale and auction company as a photographer, cataloger, project manager, and sales manager, and she has appraised personal property online since 2022.

She is a member of the International Society of Appraisers, completed the 15-hour USPAP Personal Property course in 2025, and studied art, specializing in graphic design and photography, at The Ohio State University.

Judi Burgess

Judi Burgess

ISA · CAGA
Household contentsEstate liquidationResale markets

More than 25 years researching, evaluating, and valuing personal property for resale, liquidation, auction, and charitable contributions, with estate liquidation and valuation work for private clients since 2013.

Full credentials ↓Collapse ↑

Judi's background includes more than 20 years of direct secondary-market selling, four years as a lead evaluator and lister in Goodwill Industries' e-commerce operations, estate liquidation and valuation work for private clients since 2013, and auction cataloging and curation since 2022. Her valuations rely on current market data, comparable sales, condition, quality, and observed secondary-market behavior.

She is a member of the International Society of Appraisers and the Certified Appraisers Guild of America, has completed the ISA Core Course in Appraisal Studies and the 15-hour USPAP course for personal property, and completed the American Society of Estate Liquidators course. She holds a BA in Fine Arts from Purdue University.

Jason Dolph

Jason Dolph

CAGA Certified Appraiser · AARE
Machinery & equipmentVehiclesEstate auctions

A third-generation auctioneer and certified personal property appraiser with more than 20 years in the sale and valuation of machinery, equipment, vehicles, business assets, and estates, for banks, attorneys, trustees, and private clients.

Full credentials ↓Collapse ↑

Jason has spent more than 20 years selling and valuing machinery, equipment, vehicles, business assets, and estates, and provides USPAP-compliant appraisals to banks, attorneys, trustees, and private clients. He served as a senior vice president and auctioneer at an auction firm from 2004 to 2012.

He is a Certified Appraiser of the Certified Appraisers Guild of America, holds a 200-hour Personal Property Appraiser Course certificate, has completed the 15-hour USPAP course and its update, is an Accredited Auctioneer of Real Estate of the National Auctioneers Association, and is licensed by the North Carolina Auctioneer Licensing Board. He graduated from the Mendenhall School of Auctioneering in 2003.

Business valuation

Closely held companies, LLC and partnership interests, holding companies, and private instruments in an estate. Between them they hold ASA, ABV, CFA, CVA, and CPA credentials.

Talon Stringham

Talon Stringham

CPA · ABV · CFE · ASA
American Society of AppraisersAICPA Accredited in Business ValuationAssociation of Certified Fraud Examiners
Gift & estate taxFamily limited partnershipsExpert witness

More than 24 years across business valuation, forensic and investigative accounting, and expert witness testimony. Talon has performed hundreds of gift and estate tax valuations, with subjects ranging from early-stage ventures to an automotive group with over $1.1 billion in combined sales.

Full credentials ↓Collapse ↑

Talon has spent more than 24 years in business valuation, forensic and investigative accounting, litigation support, and expert witness work. On the valuation side, he has performed appraisals supporting audited financial statements for both publicly traded and privately held companies, including purchase price allocations, 409A valuations, option, warrant, and convertible debt valuations, and goodwill impairment analyses. He has provided hundreds of valuations for gift and estate tax purposes and has valued closely held companies across a wide range of industries for financial statement preparation, ESOP, divorce, shareholder dispute, and other litigation purposes, including numerous family limited partnerships and holding companies.

His engagement history runs from early-stage bio and med-tech, software-as-a-service, and technology companies to large private groups. He served as lead valuation analyst on a high-profile Florida divorce valuation involving personal goodwill and a disputed value range exceeding $100 million, appraised every entity in a conglomerate of 19 automobile dealerships and 20 real property holding companies spanning 25 automotive and powersport brands with over $1.1 billion in combined sales, and led valuation work for a trucking company with sales in excess of $500 million in a shareholder buy-out.

On the forensic side, Talon has supervised and performed business interruption loss calculations, reconstruction of accounting records after theft, fire, and flood, and investigative accounting for criminal fraud trials, marital estates, and officer and director litigation. He has testified as an expert in personal injury, wrongful death, and wrongful termination matters, and helped defend a company against an alleged $1 billion patent and trade secret damages claim that ended in a judgment under $1 million. He also brings formal training in computer forensics and has recovered electronic evidence for divorce and employment law matters.

Talon earned a Bachelor of Arts in Accounting and a Master of Science in Accounting with a finance emphasis from Utah State University. He is a Certified Public Accountant licensed in Utah, an Accredited Senior Appraiser of the American Society of Appraisers, Accredited in Business Valuation by the AICPA, and a Certified Fraud Examiner. He has chaired the UACPA Business Valuation Committee, served as Treasurer of the Utah Chapter of Certified Fraud Examiners and of the Southern Utah Estate Planning Council, and wrote Understanding Business Valuation: An Owner's Guide to the Business Appraisal Process along with articles in The Utah Bar Journal and The Journal Entry.
Andy Frew

Andy Frew

ASA · ABV
American Society of AppraisersAICPA Accredited in Business Valuation
Closely held companiesNoncontrolling interestsGift & estate tax

More than 25 years of business valuation experience across hundreds of engagements. Andy values closely held companies, holding companies, and noncontrolling ownership interests for gift and estate tax, charitable giving, buy-sell agreements, transactions, and succession planning.

Full credentials ↓Collapse ↑

Andrew B. Frew has more than 25 years of business valuation experience and has participated in hundreds of valuation and related engagements across numerous industries. His work includes valuations of businesses and ownership interests for gift and estate tax, noncash charitable contributions, buy-sell agreements, mergers and acquisitions, business succession and exit planning, and litigation support. He has significant experience valuing closely held companies, holding companies, and noncontrolling ownership interests, and his work regularly involves the analysis of capital structures, shareholder and operating agreements, and the economic rights attached to privately held equity interests.

His industry experience includes oil and gas, particularly upstream exploration and production companies, oilfield services, manufacturing, distribution, retail, automobile dealerships, and construction and building materials.

Andy is an Accredited Senior Appraiser in Business Valuation of the American Society of Appraisers (2009) and is Accredited in Business Valuation by the AICPA. He has been a member of the American Society of Appraisers since 2007 and served as President of its Houston Chapter from 2015 to 2016. He completed the 7-Hour National USPAP Update Course in March 2024 and holds a Bachelor of Business Administration in Finance from Texas A&M University.
Justin Ramirez

Justin Ramirez

ASA · ABV · CFA
American Society of AppraisersAICPA Accredited in Business ValuationCFA Institute
Companies & partnershipsReal estate holding companiesExpert witness

Performs fair value and fair market value appraisals of companies and partnerships for tax and financial reporting, purchase price allocations, buy-sell agreements, and lending, with valuation roles at Gordon Brothers, Mercer Capital, and Weaver and Tidwell. Industry coverage runs from real estate holding companies to energy, industrial, and professional services.
Full credentials ↓Collapse ↑

Justin performs fair value, fair market value, and net orderly liquidation value analyses of companies and partnerships for tax and financial reporting, purchase price allocations, mergers and acquisitions, buy-sell agreements, and lending purposes. His clients range from individuals and their counsel, including estate and probate attorneys, to family offices and the management teams of privately held and publicly traded companies.

He is a Manager of Global Valuations at Gordon Brothers and previously held valuation roles at Mercer Capital and at Weaver and Tidwell, formerly HSSK, where he also performed audit reviews of third-party valuations. His appraisal subjects span brand-oriented retail, capital-intensive industrial, energy and utility companies, real estate holding companies, and architectural and engineering firms, with pre-revenue work in biological and medical technologies and biopharmaceutical applications. He was a key contributor to a national energy valuation publication, has been cited in Oil and Gas Investor and the Midland Reporter-Telegram, and has testified as an expert in Texas district court matters.

Justin holds a Master of Science in Finance from the University of Houston and a Bachelor of Science in Economics from Texas A&M University. He is an Accredited Senior Appraiser of the American Society of Appraisers, Accredited in Business Valuation by the AICPA, and a CFA charterholder, and he has appeared as a guest speaker and panelist at the University of Houston and Texas A&M University.

Daniel Munoz

Daniel Munoz

CVA
National Association of Certified Valuators and AnalystsNACVA Certified Valuation Analyst
Ownership interestsNotes & private equityForms 706 & 709

A Certified Valuation Analyst with about nine years of experience valuing closely held businesses, ownership interests, and financial instruments. Daniel has prepared valuations for noncash charitable contributions and for gift and estate tax, for use with IRS Forms 8283, 709, and 706.

Full credentials ↓Collapse ↑

Daniel is a Certified Valuation Analyst with approximately nine years of experience valuing closely held businesses, ownership interests, and financial instruments. His work includes financial statement analysis, valuation modeling, industry and market research, and the preparation of narrative reports and supporting schedules. He has prepared valuations for noncash charitable contributions and for federal gift and estate tax purposes, for use with IRS Forms 8283, 709, and 706, as well as for management planning, marital dissolution, and business purchases and sales.

His experience extends beyond operating businesses to real estate holding companies, restricted and preferred shares, warrants, options and other derivative instruments, promissory notes, private equity interests, and undivided interests in real estate. His analyses consider the economic rights, restrictions, payment terms, and contingencies attached to the subject interest, using option-pricing models and Monte Carlo simulation where an instrument calls for them, and probability-weighted scenario and sensitivity analysis. Industries include manufacturing, pharmaceuticals, assisted living, staffing and HR outsourcing, banking and wealth management, real estate, contracting, rail transportation, internet and hosting businesses, automobile dealerships, mining, restaurants, and waste management.

Daniel earned the Certified Valuation Analyst (CVA) credential from the National Association of Certified Valuators and Analysts in 2018 and is a member of NACVA. He holds a Bachelor of Science in Business with a concentration in Finance.

Raymond Ghelardi

Raymond Ghelardi

ASA
American Society of Appraisers
Tax valuationsValuation reviewIntangible assets

More than 35 years of valuation experience across tax and financial reporting, including leadership of national valuation practices at BDO's valuation arm and CBIZ Valuation Group, and review of valuations prepared by other experts.

Full credentials ↓Collapse ↑

Raymond has over 35 years of experience valuing the securities and intangible assets of public and private corporations for financial reporting and tax purposes, including engagements under ASC 805, ASC 350, and 409A. He is the Managing Partner of Business Valuation Center's New York and Tampa offices and an executive of its parent holding company, and he has long been responsible for reviewing valuations prepared by other experts on behalf of accounting practice clients.

His career includes senior leadership across several national valuation practices: Director at GBQ Consulting, where he headed the New York office; Managing Director, Eastern Region Valuation Services at Ceteris; and Managing Director of Trenwith Valuation, the valuation arm of BDO, where he led teams on financial reporting and tax valuation projects and served as one of three members of the National Leadership Committee for BDO's valuation practice. Earlier, as Chairman of Valuation Counselors Group, he managed all aspects of the firm's business and rebuilt it into a national leader before directing its sale to CBIZ, a publicly traded company, in 1997. He also served as Senior Vice President at Management Planning, Inc. in Princeton, where he helped develop and implement the firm's corporate valuation practice.

Raymond holds an MBA from Emory University, a Master in City Planning from Harvard University, and a Bachelor of Science from Pennsylvania State University. He is an Accredited Senior Appraiser and Senior Member of the American Society of Appraisers and a past president of its Princeton chapter.

Steve, Anne, Ashley, Henry, Shelly, Marnie, Robert, Jasmani, Brandy, Judi, Jason, Talon, Andy, Justin, Daniel, and Raymond are among the appraisers on our team.

Client Reviews

What our estate clients say

Reviews from families, executors, and advisers who needed property or a business interest valued for an estate, a trust, or a probate court, posted on Google.

My mother passed away in August 2023 and unfortunately, in the state of Ohio, motorhomes are not transferable on death and was going to have to go through probate court. After speaking with an attorney, I was informed I needed an appraisal. Due to my hectic work schedule and family schedule, I was looking for someone who could do this online, without needing an appointment.

After a quick Google search I came across Joe at AppraiseItNow Inc., and instantly felt relief. A quick inquiry led to a few emails back and forth, a very reasonable cost to have the motorhome appraised and all the information needed to submit to get this taken care of.

Joe was patient, worked with me as it was going to take a few weeks before I was able to supply the needed images/documents and payment, and less than a week later of submitting it I received the appraisal.

His communication is next to none! He responds very quickly, is kind and extremely helpful.

If I need anything in the future, I will not hesitate to reach out again! Thank you again! I will forever be in your debt!

Brandy F.Motorhome appraisal for probate court · Mentor, OH

I needed an appraisal for Probate Court, so I could get the boat and motor title in my name. The AppraiseItNow team was great, quick turn around, outstanding service. I would definitely use them again.

Steven K.Boat appraisal for probate court · Dayton, OH

This team is so easy to work with. They are very professional and pleasant, and respond quickly to any questions. They are knowledgeable and complete their appraisal quickly. I feel their fee is reasonable for the work they do. They are properly licensed so I feel they can be trusted, especially after speaking with them. It is clear they know what they are talking about. Their process is easy to follow and complete. I highly recommend the AppraiseItNow team and look forward to working with them again.

Janet K.Estate distribution · Vero Beach, FL

Working with AppraiseItNow on two mobile homes' appraisals was probably the easiest thing I have ever done. All of the staff, especially Aron, we're super knowledgeable, courteous, and professional in everyone of our communications. I would gladly refer them to anyone!!

Coke F.Mobile home appraisals for probate · Columbia, SC

Reached out to Joe and Team in a difficult spot. A client gifted 5 Private Market LPs to a trust and needed a valuation and had a 5 week window to get it done. We had a call with Joe and he outlined what information was needed and provided an estimated cost. We received a detailed engagement letter with final cost. Joe was confident his team could get the job done on time. We received the draft valuation in approximately 4 weeks which needed to be reviewed by tax and legal council. When it was all said and done the final report was delivered a couple days earlier than originally promised which was a huge weight lifted off the client and his advisors. Communication is key and AppraiseItNow did a great job from start to finish and delivered exactly what they promised. Great experience!

Ryan T.Business valuation for gift tax · Annapolis, MD
In Depth

Detailed case studies

What each engagement covered and the rules that applied. Every report concludes fair market value as of the date the estate needed. Amber items are rules worth confirming with the estate's attorney or accountant. Photos are illustrative.

A dining room with a set table, a china cabinet, rugs, and paintingsAn antique chest with a porcelain vase, a mantel clock, a tea set, and a small painting
Case Study 01

Contents of a family home, room by room, for an estate tax return

Household Contents
Property
Furniture, rugs, paintings, dishes and glassware, beds, and the rest of a single-family home's contents, limited to the items the decedent owned
Purpose
Estate tax return (Form 706)
Valuation Date
Date of death
Inspection
In person, room by room

What the appraisal covered

Fair market value
  • A walk-through of every room, with items named individually and lower-value items in the same room grouped
  • Only the decedent's property: items belonging to others in the household were left out
  • Items already appraised elsewhere were excluded, so nothing was valued twice
  • Fair market value of each item or group as of the date of death

Rules in play

Treas. Reg. §20.2031-6
  • Household and personal effects are itemized room by room; articles in the same room worth no more than $100 each may be grouped
  • Where articles of marked artistic or intrinsic value pass $3,000 in total, an expert appraisal is filed with the return under oath
  • Form 706 is due nine months after the date of death, with a six-month extension of time to file available on Form 4768
■ Amber items: confirm with the estate's attorney or accountant
ReportFair market value · date of death
A pearl necklace, a sapphire bracelet, emerald earrings, and a diamond ringA mid-century dining table and chairs by a window
Case Study 02

Furniture and jewelry for a Maryland probate inventory, after the house was cleared

Probate Inventory
Property
Household furniture, and an assortment of costume and suspected fine jewelry
Requested By
The personal representative
Valuation Date
Date of death, valued retrospectively
Inspection
From the personal representative's photos and inventory list: the property was no longer accessible

What the appraisal covered

Fair market value
  • Fair market value as of the date of death, for the inventory filed with the Register of Wills
  • Related household items valued together as lots, so low-resale pieces were not itemized at more cost than they were worth
  • Jewelry identified from close-up photos of the settings and stones, with size references
  • A report with the appraiser's signed certification, USPAP compliance statement, and qualifications

Rules in play

Probate inventory
  • Estates file an inventory of the decedent's property with date-of-death values
  • Our fee is fixed in the engagement letter before work starts and never depends on the values found
  • Where photos stand in for an inspection, the report states the extraordinary assumptions used, which might have affected the results
■ Amber items: confirm with the estate's attorney or accountant
ReportFair market value · date of death
Older cars stored in a garageA motorhome on a mountain roadA motor yacht tied up at a marina dock
Case Study 03

Cars, boats, and motorhomes for Ohio probate courts

Vehicles & Boats
Property
A pontoon boat and outboard motor; a motorhome; a horse trailer with living quarters; and one estate with nine cars, a trailer, a jet ski, two snowmobiles, and a boat
Purpose
Probate court, to settle the estate and transfer titles
Valuation Date
Date of death, in some cases years earlier
Inspection
From the family's photos, VINs or hull numbers, and mileage

What the appraisal covered

Fair market value
  • Year, make, model, VIN or hull number, mileage, and condition, from the family's photos and details
  • Comparable sales as of the date of death, including a boat and motor that had sat out of the water for years
  • One report listing every vehicle, where an estate held several

Rules in play

Fair market value
  • In one estate, the probate court asked for an appraisal before it would put the boat and motor in an heir's name
  • Fair market value is not a forced-sale price, and is measured in the market where such items are most commonly sold to the public
  • Whether a vehicle can pass outside probate depends on the state and how it was titled
■ Amber items: confirm with the estate's attorney or accountant
ReportFair market value · date of death
Gold and silver coins laid out on a slate tray
Case Study 04

A late father's coin collection, valued for the estate and for three heirs

Coins
Property
A late father's coin collection
Purpose
Dividing the collection among three siblings, and date-of-death values for the estate's tax reporting
Valuation Date
Date of death
Inspection
From the family's photos

What the appraisal covered

Fair market value
  • Each coin and set identified, with its condition assessed from the photos
  • Comparable sales as of the valuation date, from the markets where collectors buy
  • Itemized values the three heirs could divide the collection by

Rules in play

Basis and division
  • The value reported generally becomes each heir's income tax basis, so it follows the coins into any later sale (IRC §1014)
  • Coin and stamp collections count toward the $3,000 of articles of artistic or intrinsic value that call for an expert appraisal with Form 706
■ Amber items: confirm with the estate's attorney or accountant
ReportFair market value · date of death
An electric guitar beside a mixing desk in a studioFramed oil paintings hung on a gallery wall
Case Study 05

Six guitars and a painting, split between two specialists

Instruments & Art
Property
Six vintage and signed guitars, and a mid-1960s painting by an American artist
Requested By
The executor, with the estate's attorney
Valuation Date
Date of death
Appraisers
Our musical instrument appraiser for the guitars, and a fine art appraiser for the painting

What the appraisal covered

Fair market value
  • Each guitar's maker, model, year, condition, and signatures, and what those do to value
  • The painting's artist, size, period, and the market for comparable works
  • Two reports, scoped together on the same date-of-death basis

Rules in play

Date of death
  • Values are taken at the date of death unless the executor elects the alternate valuation date, which applies to the whole estate and only where it lowers both the gross estate and the tax (IRC §2032)
  • Paintings and other articles of marked artistic value count toward the $3,000 that calls for an expert appraisal filed with Form 706 under oath
■ Amber items: confirm with the estate's attorney or accountant
ReportsFair market value · date of death
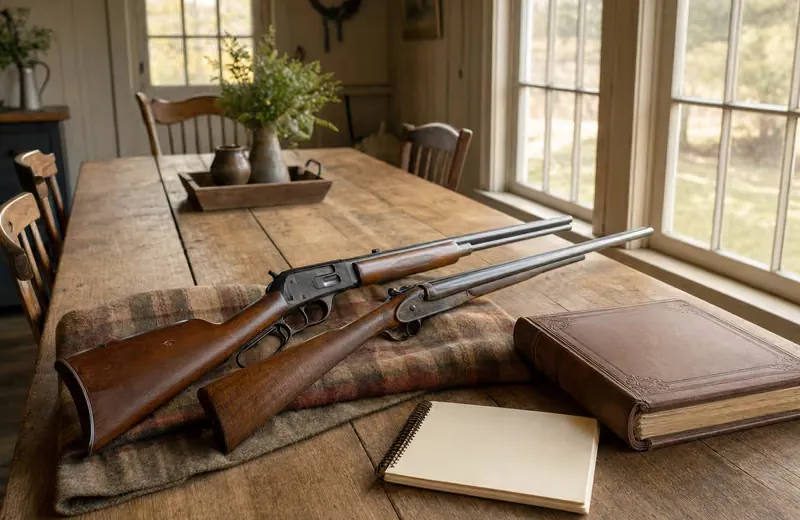
A vintage revolver in an open, felt-lined wooden case beside a clipboardA lever-action rifle and a side-by-side shotgun on a farmhouse dining table
Case Study 06

An antique firearms collection, three dozen pieces

Firearms
Property
36 antique firearms, each photographed from several angles
Purpose
Settling the estate
Valuation Date
Date of death
Inspection
From the family's photos

What the appraisal covered

Fair market value
  • Maker, model, serial number, configuration, originality, and condition of each firearm, from the photos
  • Comparable sales for each piece as of the date of death
  • An itemized report for the personal representative

Rules in play

Fair market value
  • The price between a willing buyer and a willing seller, neither under any compulsion and both with reasonable knowledge of the relevant facts (Treas. Reg. §20.2031-1(b))
  • Not a dealer's buying price or a forced-sale price
ReportFair market value · date of death
Two wristwatches on a display standA vintage green roadster parked in front of a white farmhouse
Case Study 07

Watches and a collector car, valued as of a date of death more than four years earlier

Retrospective
Property
A gold Rolex, a silver Cartier watch, and a Ferrari
Purpose
Estate tax
Valuation Date
Date of death, more than four years before the appraisal
Appraisers
One appraiser for the watches, and our vehicle appraiser for the car

What the appraisal covered

Fair market value
  • Comparable sales from around the date of death, not today's prices
  • Condition as of the date of death, from photos and the family's records
  • Two reports with the same retrospective effective date

Rules in play

Retrospective value
  • USPAP allows an effective date in the past; the report states it and uses only market evidence that was available as of that date
  • The value reported generally becomes the heir's income tax basis when the car or watches are later sold (IRC §1014)
ReportsFair market value · date of death
A corporate seal embosser beside operating documents on a deskA desk with a financial model on the monitor in a bright office
Case Study 08

A decedent's interests in three small New York LLCs, for an estate tax return

Business Interests
Property
The decedent's interests in three small LLCs: two non-operating companies being wound down that held only cash, and a land-holding company with two parcels of vacant land
Requested By
The estate's attorney
Valuation Date
Date of death
Appraisers
Our business valuation team, with separate appraisals of the land referenced in the report

What the appraisal covered

Fair market value
  • Each company's assets and liabilities as of the date of death, from bank statements, tax returns, and the operating agreement
  • For the two cash-only companies, value tied to the cash on hand at the date of death
  • For the land-holding company, separate appraisals of the two parcels, referenced in the business valuation
  • The decedent's ownership interest in each company, and the rights the operating agreement attached to it

Rules in play

Treas. Reg. §20.2031-3
  • An interest in a business is valued on all relevant factors, including a fair appraisal of all its assets and its demonstrated earning capacity
  • Whether a minority or restricted interest is worth less than its share of the company's assets depends on the facts and the operating agreement
  • Form 4768 extends the time to file Form 706 by six months
■ Amber items: confirm with the estate's attorney or accountant
ReportsFair market value · date of death
An open-plan company office with desks and a glass meeting roomA desk with a financial model on the monitor in a bright office
Case Study 09

Two family-held operating companies, valued for an estate plan

Business Interests
Property
Two family-held operating companies, a manufacturer and a parts-and-service business
Purpose
Estate planning
Valuation Date
A set planning date
Appraiser
Our business valuation team, from the companies' financial statements

What the appraisal covered

Fair market value
  • Each company's historical and most recent financial statements
  • Income, market, or asset approach, as the facts support
  • Fair market value of the interests the plan transfers, as of the planning date

Rules in play

Rev. Rul. 59-60
  • Closely held businesses are valued on the factors the IRS sets out in Rev. Rul. 59-60, including earning capacity, financial condition, and the market for similar companies
  • Gifts made under an estate plan are reported on Form 709; the appraisal supports the values reported
■ Amber items: confirm with the estate's attorney or accountant
ReportsFair market value · planning date